 App DevelopmentBest Apps for Finance Professionals, by CategoryThe most useful apps for finance professionals by category, from budgeting and accounting to market news and security, and when to build your own.
Apps Like Cash App: Money Transfer Alternatives Compared
Venmo, PayPal, Zelle, Apple Cash, Revolut, Wise and more compared as Cash App alternatives, plus what it takes to build a payments app of your own.
The most practical apps like Cash App in the US are Venmo, PayPal, Zelle, Apple Cash, Revolut and Wise, with Western Union and MoneyGram for sending money abroad. Venmo and PayPal are closest for everyday payments between friends, Zelle is best for fast bank to bank transfers, and Wise or Revolut suit people who move money across currencies. The right pick depends on who you pay, where they are and how quickly the money needs to arrive.
Below we compare the main options, explain what to check before you trust an app with your money, and cover what a business needs to know if it wants to build a payments app of its own.
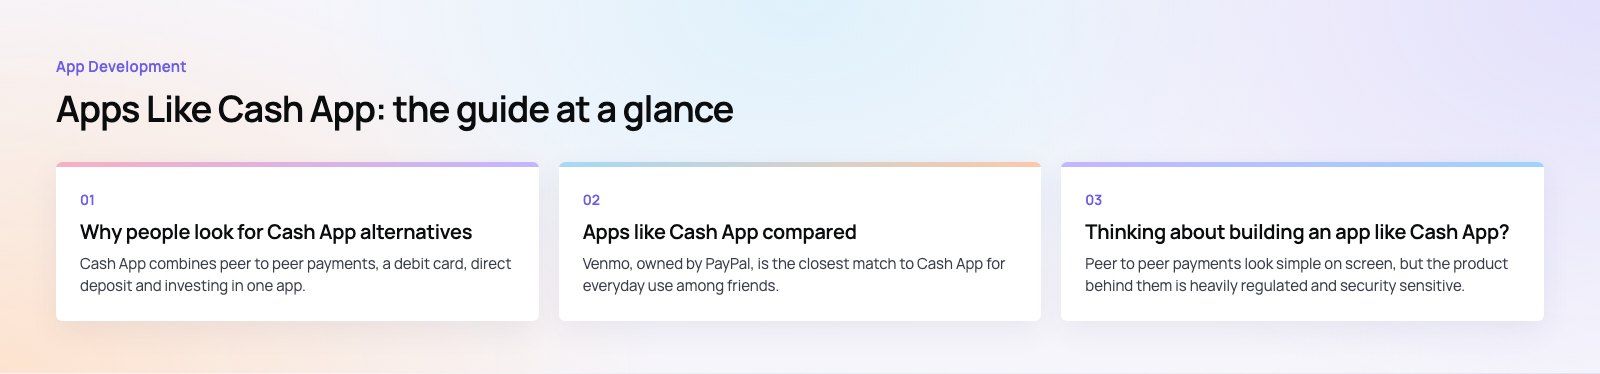
Why people look for Cash App alternatives
Cash App combines peer to peer payments, a debit card, direct deposit and investing in one app. It is popular, but it is not always the best fit. Common reasons to look elsewhere include:
- Friends or family already use a different app.
- You need to send money internationally, which Cash App does not focus on.
- You want transfers to go straight into a bank account without holding a balance in the app.
- You prefer stronger purchase protection for paying businesses.
- You want a backup option in case one account is locked or under review.
How to choose an app like Cash App
- Who you are paying. The best app is often the one the other person already uses.
- Speed. Some transfers arrive in minutes, others take one to three business days unless you pay for instant delivery.
- Fees. Look at instant transfer fees, card funded payment fees and currency conversion costs.
- Protection. Payments to friends usually have little or no protection if you are scammed. Payments marked as purchases sometimes do.
- Security. Look for app level PINs, biometric sign in, two factor authentication and transaction alerts.
- Coverage. Check which countries, currencies and devices are supported.
Apps like Cash App compared
| App | Best for | Where it works | Main limitation |
|---|---|---|---|
| Venmo | Splitting bills with friends | US | Payments between friends have limited protection |
| PayPal | Paying people and online stores | Many countries | Fees on some transfers and currency conversion |
| Zelle | Fast transfers between US bank accounts | US, inside participating bank apps | Little protection once a payment is sent |
| Apple Cash | Quick payments between iPhone users | US | Apple devices only |
| Revolut | Holding and exchanging several currencies | Many countries | Some features depend on plan and country |
| Wise | Low cost international transfers | Many countries | Not built for social, everyday splitting |
| Western Union | Cash pickup abroad | Global agent network | Fees and exchange margins can be higher |
| MoneyGram | Cash pickup and bank deposits abroad | Global agent network | Fees and exchange margins can be higher |
Venmo
Venmo, owned by PayPal, is the closest match to Cash App for everyday use among friends. You can split bills, pay with a linked bank account or card, and move your balance to the bank for free in standard time or for a fee instantly. Its social feed is optional and can be set to private. Venmo works for US users only.
PayPal
PayPal is the broadest option. It handles payments to friends, purchases from online stores and transfers to many countries. Paying a business through PayPal usually comes with purchase protection, which friend to friend apps rarely offer. Fees apply to some transfers and currency conversions, so check the cost before sending abroad.
Zelle
Zelle moves money directly between US bank accounts, usually within minutes when both people are enrolled. It now runs inside the apps and websites of participating banks and credit unions, since its standalone app stopped handling payments in 2025. Zelle is best used with people you know and trust, because a payment generally cannot be reversed once it is sent.
Apple Cash
Apple Cash lets iPhone users send and receive money in Messages and Wallet, with Face ID or Touch ID confirming each payment. It works with Apple Pay in stores and online. It is convenient if everyone you pay uses Apple devices, and not useful if they do not.
Revolut
Revolut combines a spending account with multi currency balances, exchange, transfers and budgeting tools. It suits people who travel or deal in several currencies. Which features are available, and what they cost, depends on your plan and your country.
Wise
Wise, formerly TransferWise, specializes in international transfers and shows the exchange rate and fee before you send. You can hold balances in many currencies and receive payments with local account details in several countries. It is not designed for splitting a dinner bill, but it is often a strong choice for sending money overseas.
Western Union and MoneyGram
Both run large global networks of agent locations, so recipients can collect cash where bank access is limited. Their apps also support bank deposits and, in some markets, mobile wallet payouts. Compare their fees and exchange rates against Wise or PayPal before each transfer.
Staying safe with money transfer apps
- Only send money to people you know. Scammers prefer instant, irreversible payments.
- Double check the recipient's name, phone number or username before you confirm.
- Turn on two factor authentication and an app PIN.
- Never share sign in codes, even with someone claiming to be from the app's support team.
- Use the purchase option, not the friends option, when paying a business that supports it.
- Keep the app and your phone's operating system updated.
Thinking about building an app like Cash App?
Peer to peer payments look simple on screen, but the product behind them is heavily regulated and security sensitive. Here is what a business should plan for.
Decide on your model
Some companies build a full wallet that holds customer balances. Others build a front end on top of a licensed partner bank or payments provider that holds the funds. The second route is far faster to launch, because the partner carries much of the licensing burden.
Licensing and compliance
In the US, businesses that transmit money generally need to register with FinCEN as a money services business and hold money transmitter licenses in the states where they operate, unless a partner covers this. You will also need know your customer checks, anti money laundering monitoring, sanctions screening and clear dispute handling.
Security
- Strong customer authentication with biometrics and device binding.
- Encryption of data in transit and at rest.
- Card data kept out of your systems by using a compliant processor.
- Fraud rules that flag unusual amounts, new devices and new recipients.
- Full audit trails for every balance change.
Core features
- Onboarding with identity verification.
- Linking bank accounts and cards.
- Send, request and split payments.
- Transaction history and receipts.
- Notifications for every payment.
- An admin console for support, refunds and compliance review.
Technology choices
Cross platform frameworks such as React Native or Flutter let one team ship iOS and Android together, which suits most new payment apps. The back end matters more than the front end: a ledger that never loses a cent, idempotent payment calls, and reliable reconciliation with your banking partner.
Start small
Launch with one use case, such as payments within a community, a workplace or a marketplace, before trying to compete with general purpose apps. A focused product is easier to secure and easier to get adopted.
If you are planning a payments product, our mobile app development team can help you scope it, and our payment integration work covers connecting apps to licensed providers. The Purpose Payment case study shows a payments app with portals and an API, and you can see more of our fintech work or book a product scoping session.
Frequently asked questions
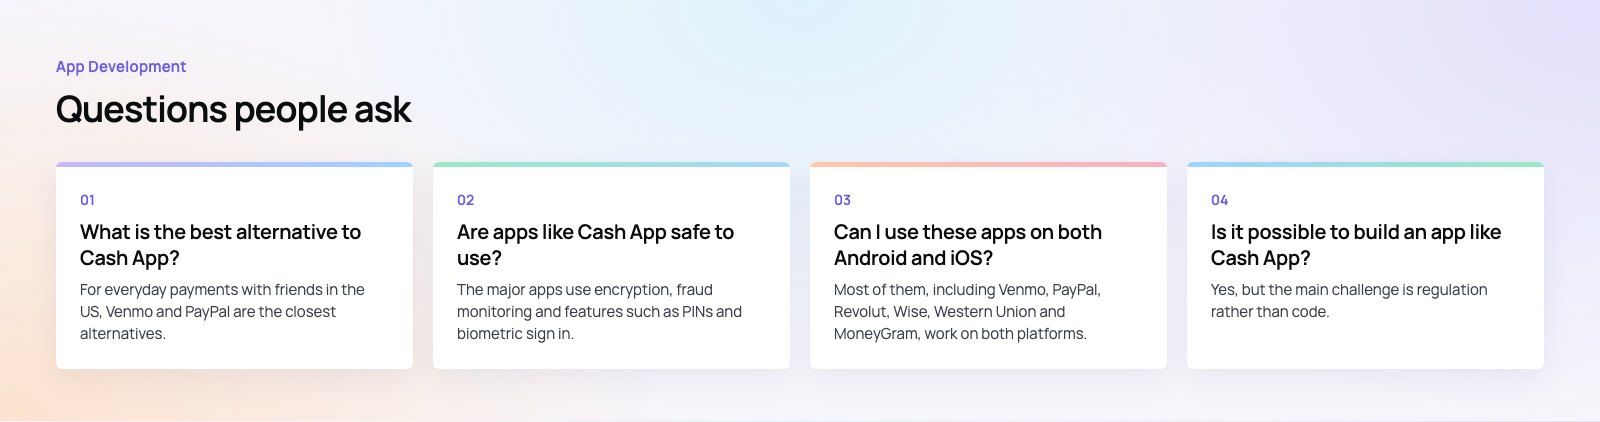
For everyday payments with friends in the US, Venmo and PayPal are the closest alternatives, and Zelle is the fastest option for moving money straight between bank accounts.
For international transfers, Wise and Revolut are usually better suited. The most practical choice is often the app the people you pay already use, since both sides need an account for most of these services.
App DevelopmentBest Apps for Finance Professionals, by CategoryThe most useful apps for finance professionals by category, from budgeting and accounting to market news and security, and when to build your own. App DevelopmentApps Like Dave: Cash Advance and Earned Wage Access OptionsEarnIn, Brigit, MoneyLion, Chime, Branch and other apps like Dave compared by how they charge, plus what it takes to build a wage access app.
 App DevelopmentApps Like Klarna: Flexible Payment Options and How to Build OneAffirm, Afterpay, Sezzle, Zip, PayPal Pay in 4, Splitit and Perpay compared as Klarna alternatives, plus a seven step plan for building a BNPL app.
Tell us what the business needs. We will tell you what to build first.
Schedule a free consultation and get a written recommendation, with costs, before you commit to anything.
Get in touchPROVEN RESULTS
4.7 / 5verified reviews on Google